Aegon provides several pension platforms and has also used the Scottish Equitable name for older plans. If you have changed jobs or mislaid your correspondence, you may remember the provider without knowing which Aegon service holds the pension. The quickest route is usually to identify your “unique number”—the customer, wrapper, account, plan or policy number shown on your documents—and use Aegon’s login finder to choose the right service.
What is a “lost pension”?
A lost pension is one you can no longer access or confidently include in your records. It remains associated with the policy and may still be invested, so its value is not fixed. Finding it allows you to update your details, read current statements and understand what you have accumulated for retirement.
Reasons to Trace Your Aegon Pension
You might want to trace your pension if:
A former employer enrolled you with Aegon or Scottish Equitable.
You have an account number but do not know which Aegon login to use.
You changed address, surname, phone number or email.
You are building a complete view of your pension savings.
Steps to Find Your Aegon Pension
Use Aegon’s login finder
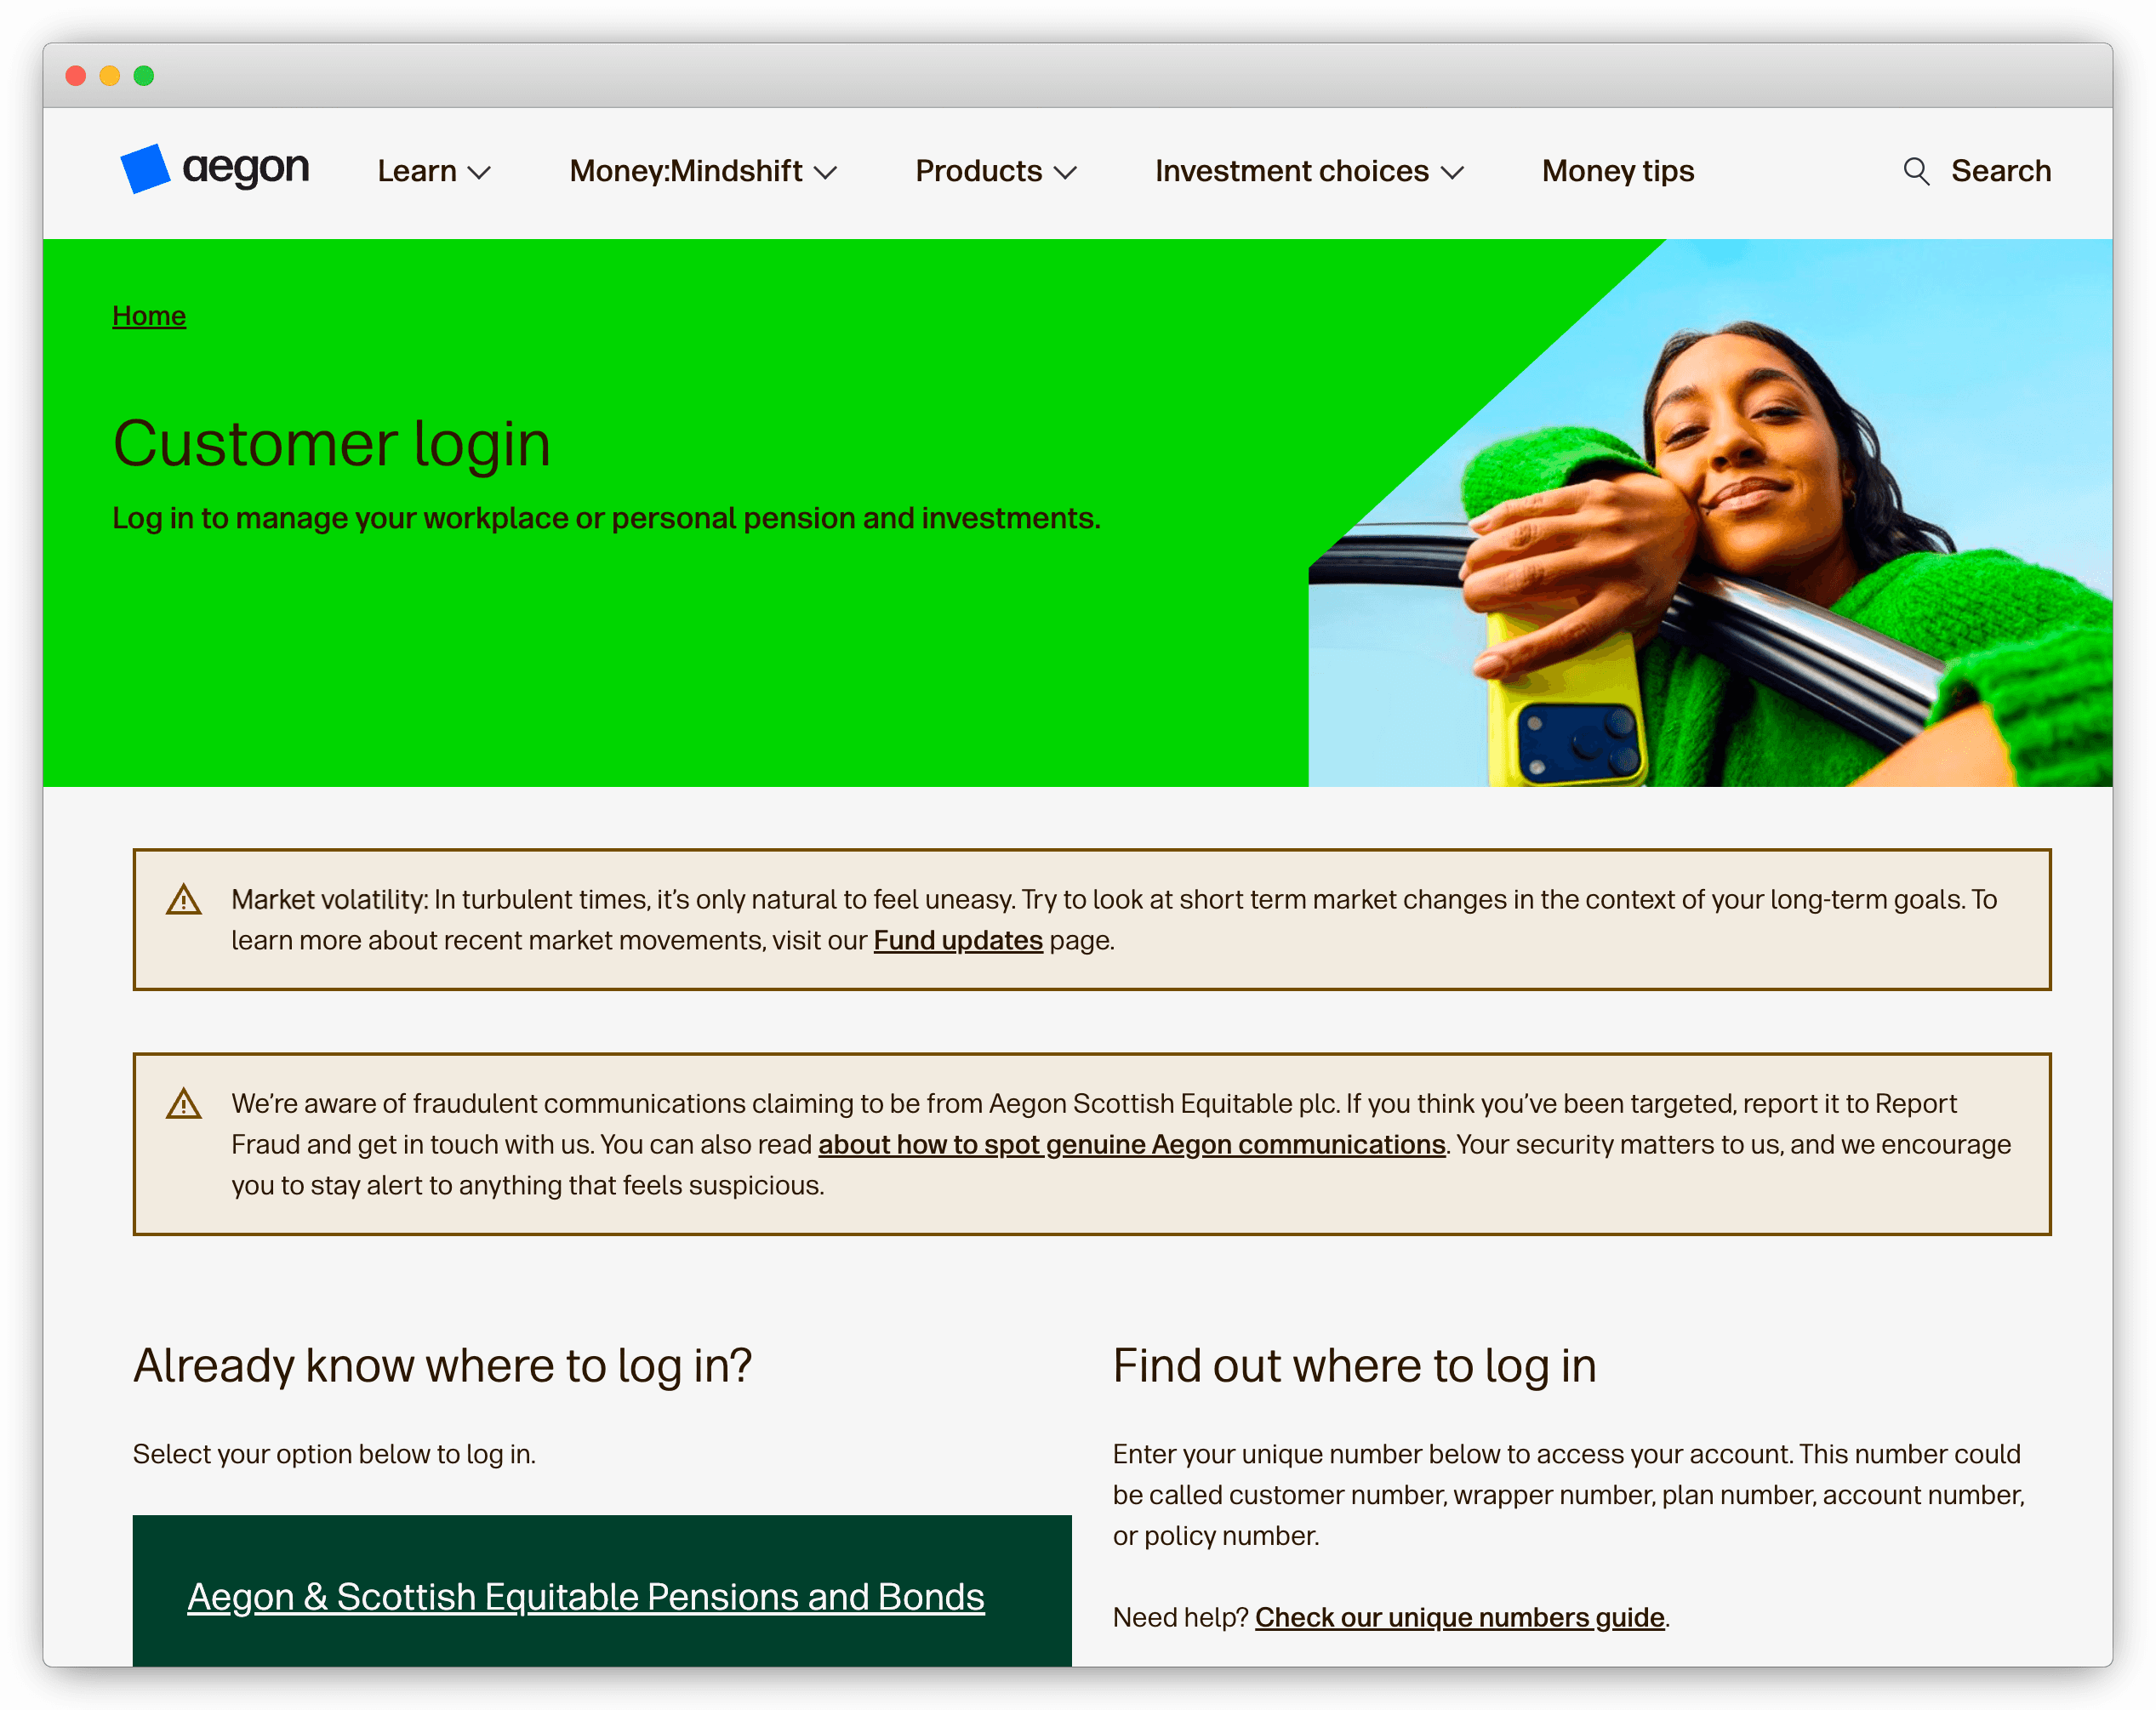
Visit the Aegon customer login page. It lists services including Aegon Retirement Choices, One Retirement, Retiready, Aegon Platform, TargetPlan and older Aegon or Scottish Equitable plans. If you are unsure which route applies, open the unique-number guide on the page and compare its examples with your statement. Different services use different kinds of reference number, so choosing the correct route matters.
Contact the support team for that service
If online access does not work, use Aegon’s support page and select the product or platform you identified. There is no single login or contact route for every Aegon pension. Prepare your full name, date of birth, National Insurance number, previous addresses, former employer and any customer, wrapper, plan or policy number you have. The team will need to verify your identity before discussing a record.
Search your paperwork for the unique number
Check annual statements, welcome packs, contribution letters and old emails for “Aegon”, “Scottish Equitable”, “TargetPlan”, “Retiready”, “ARC”, “customer number” or “policy number”. A payslip may show pension deductions without the individual account number, but it can confirm the employer and approximate membership dates. Former HR or payroll staff may also know the scheme’s formal name.
Try the government Pension Tracing Service
If the employer is your only reliable clue, search the free Pension Tracing Service. The service provides contact details for schemes and providers; it does not search personal balances or prove that you are a member. Contact the scheme it identifies and provide the information requested. MoneyHelper’s lost-pension checklist is useful preparation.
Use a financial adviser for extra help
An independent financial adviser can help untangle several Aegon services or older policies and request information with your written permission. They can also explain the plan after it is located. Advice normally carries a fee, so confirm the terms first.
Use Penny (or a similar tracing service)
If you are not certain Aegon was the provider, Penny can help search for old workplace pensions using your employment history and personal details. This may save you from testing several provider logins at random. The provider may still ask for supporting information before confirming a pension match.
Ready to Track Down Your Aegon Pension?
The key is to match the plan with the correct Aegon service. Start with the wording and reference number on your oldest document, use the login finder, and move to the product-specific support route if needed. If you have no documents, an employer name and approximate dates are still enough to begin a structured search.
Penny can help
Download the Penny Pension app
Find your old workplace pensions
Manage your pensions in one app